Summary
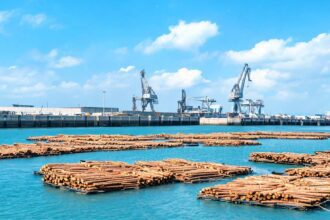
Export log prices rose to a 20-month high in November 2026, with the FICA November 2026 price schedule showing A-grade 3.9-metre logs at NZ$134/JAS, A-grade 5.9-metre at NZ$137/JAS and AO-grade 5.9-metre at NZ$140/JAS. Stand Forestry chief operating officer Marcus Musson said the rise was driven less by a supply-demand imbalance than by lower freight rates and currency factors: the Reserve Bank holding the official cash rate steady has weighed on the New Zealand dollar, the renminbi has climbed to a four-year high against the US dollar, and Handysize freight rates have eased on softer global demand. Daily outturn at Chinese ports is about 65,000 cubic metres, and inventories have fallen 270,000 cubic metres since September to 2.3 million cubic metres, though that remains above the 2 million cubic metre threshold Musson describes as key.
China's manufacturing PMI fell to 49.3 in October, in contraction territory. Cost pressures are pronounced: harvesting and log-trucking fleets burn more than 300 million litres of diesel a year, and the industry is paying more than NZ$400 million a year more in fuel costs than in October 2025. Laurie Forestry's October data showed traders still selling at a loss of about US$4 per cubic metre, with a CFR cost of US$132 against an average selling price of US$128.
The market is watching whether Chinese restocking after Chinese New Year and a pick-up in New Zealand's summer harvest can support prices.
Commentary
New Zealand export log prices have climbed to a 20-month high, but the driver is not strong Chinese demand — it is a weaker New Zealand dollar, a stronger renminbi and softer freight rates. For the small and medium-sized New Zealand forestry businesses that depend on exports, this looks more like a brief window than a trend reversal. Chinese port inventories have fallen to 2.3 million cubic metres but remain above the key 2 million threshold, and the manufacturing PMI has contracted to 49.3, leaving demand without sustained support.
Profit distribution along the supply chain is uneven: forest owners benefit from higher wharf-gate prices, but harvesting and transport contractors face more than NZ$400 million a year in extra fuel costs, and traders are still losing about US$4 per cubic metre. After two years of downturn, the price recovery offers only breathing space. The contest between Chinese restocking after Chinese New Year and a larger New Zealand summer harvest will determine whether prices hold.
SMEs should watch freight and currency movements rather than fixate on log prices alone, and consider hedging or market diversification to reduce risk.
Keywords: export log prices, 20-month high, FICA price schedule, NZD exchange rate, Handysize freight rates, Chinese port inventories, manufacturing PMI, fuel costs, trader losses, post-Chinese New Year trend
Photo by Kerin Gedge on Unsplash
Source: b2bnews.co.nz
Disclaimer: This article is compiled from publicly available sources for general information only. The analysis and commentary are editorial opinions. MiDeer Observer does not guarantee the accuracy or completeness of the information provided. Readers should seek independent professional advice before relying on this content, or contact us for more information.